
Texas Property Insurance Claim Help
Texas Property Insurance Claim Deadlines: A Guide for Policyholders
When your home or business has been damaged, every day without a clear answer can create more stress, more uncertainty, and more pressure to accept less than your claim may require.
Texas law establishes several deadlines for acknowledging, investigating, accepting, rejecting, and paying many insurance claims. Those deadlines are not always as simple as counting a fixed number of days from the date of loss. The timeline may depend on when the insurer receives notice, whether additional information is requested, when the insurer receives the materials needed to evaluate the claim, and whether special policy or statutory provisions apply.
Texas Property Claim Timelines: What You Need to Know
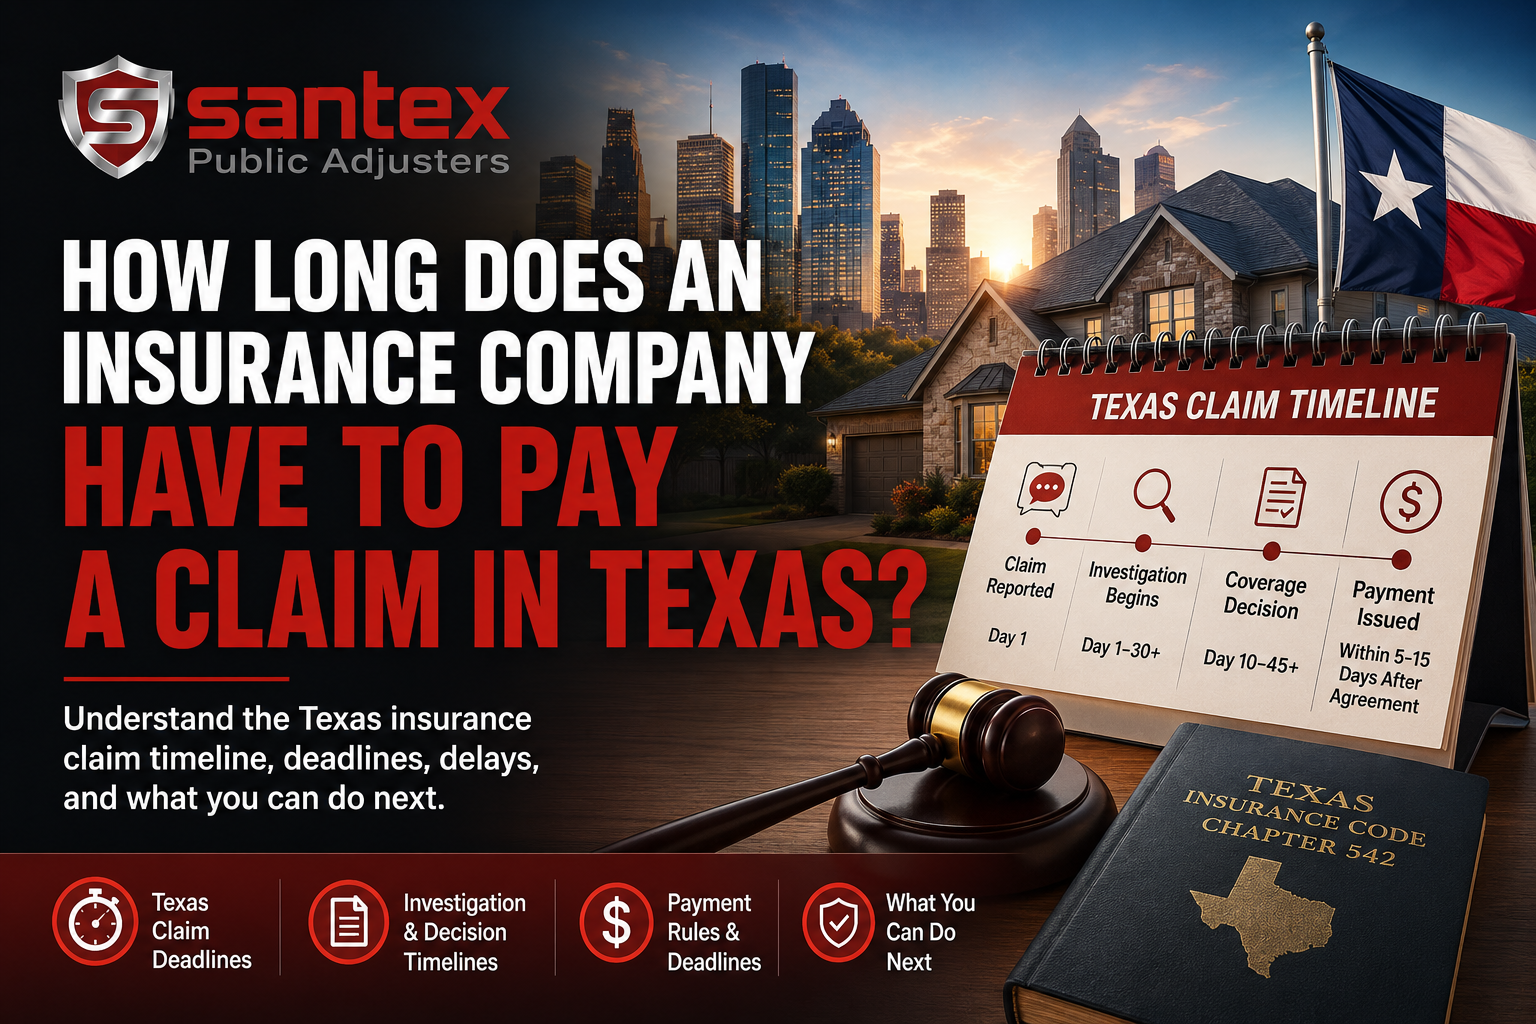
In many Texas property claims, an insurer generally must acknowledge the claim and begin its investigation within 15 days after receiving notice. After receiving the information it reasonably requires, the insurer generally has 15 business days to accept or reject the claim, although it may extend that decision period in certain circumstances.
Once the insurer notifies the policyholder that it will pay the claim, payment is generally due within five business days. A separate Texas provision may apply when payment is delayed more than 60 days after the insurer receives the reasonably requested claim materials. Surplus-lines insurers and some specialized policies may follow different timelines.
Is Your Property Claim Taking Too Long?
Santex Public Adjusters represents policyholders—not insurance companies. We can review your claim history, carrier correspondence, damage documentation, estimates, and payment activity to help you understand the next practical step.
We Listen. We Plan. You Recover.
Texas Property Insurance Claim Deadlines at a Glance
The following timeline summarizes several commonly applicable requirements under Texas Insurance Code Chapter 542. It is a general guide, not a calculation of the deadline for a particular claim.
Stage 1
Claim Acknowledgment
The insurer generally must acknowledge the claim, begin its investigation, and request the information it reasonably believes will be needed within 15 days after receiving notice of the claim.
Stage 2
Investigation
The carrier reviews the reported loss, inspects the property, evaluates coverage, and may request photographs, inventories, estimates, receipts, statements, or other supporting materials.
Stage 3
Coverage Decision
After receiving the items, statements, and forms it requires, the insurer generally must notify the policyholder in writing that the claim is accepted or rejected within 15 business days.
Stage 4
Payment
After notifying the policyholder that it will pay all or part of the claim, the insurer generally must issue payment within five business days, subject to applicable conditions and exceptions.
The Most Important Timing Distinction
The date you report the claim is not necessarily the date every later deadline begins.
Some deadlines run from the date the insurer receives notice of the claim. Other deadlines run from the date the carrier receives the items, statements, and forms it reasonably requested to evaluate the loss.
This is one reason documentation matters. A policyholder should be able to show what was submitted, how it was submitted, who received it, and when it was received.
What You Should Document
A detailed claim record can help establish the actual timeline and reduce confusion when the insurer requests more information.
- The date and method used to report the claim
- The claim number and assigned adjuster’s contact information
- Every email, letter, portal message, and text message
- Inspection dates and the names of people who attended
- Every document requested by the carrier
- Proof showing when requested documents were delivered
- The carrier’s estimate, coverage letter, and payment explanation
- Contractor estimates, invoices, photographs, and repair documentation
How Long Can an Insurance Company Investigate a Claim in Texas?
After the insurer receives all items, statements, and forms required to secure final proof of loss, it generally must provide written notice accepting or rejecting the claim within 15 business days.
When the insurer cannot accept or reject the claim within that period, it may notify the policyholder that additional time is needed. Texas law generally allows the insurer to extend the decision period to the 45th day after it gives that notice.
A longer investigation is not automatically improper. Complex causation disputes, multiple areas of damage, expert inspections, missing documents, questions about prior damage, and disagreements over scope can all affect the process. The critical question is whether the carrier is communicating clearly, making reasonable requests, and moving the investigation forward.
How Long Does the Insurer Have to Pay After Approving a Claim?
After the insurer provides notice that it will pay the claim or part of the claim, payment generally must be issued within five business days.
When payment is conditioned on an act the policyholder must perform, the payment period generally begins after that act is completed. Eligible surplus-lines insurers may have a different payment period.
An insurer may also issue an undisputed payment while other portions of the claim remain under review. Receiving a partial payment does not necessarily mean every disputed item has been resolved.
Why Property Insurance Claims Get Delayed
Some delays arise from genuine claim complexity. Others result from poor communication, repeated requests, incomplete evaluations, or unresolved disagreements.
- Missing or incomplete claim documents
- Repeated requests for information already submitted
- Disagreement over the cause of damage
- Disagreement over repair scope or pricing
- Multiple inspections or reinspections
- Requests for engineering or specialist reports
- Questions about wear, deterioration, or prior damage
- Large-scale storm or catastrophe claim volume
- Internal reassignment of the insurance adjuster
- A partial denial or coverage dispute
Warning Signs That a Delay May Be Becoming a Claim Dispute
A slow claim does not always mean the insurer is acting improperly. However, these patterns deserve closer attention:
- ✓
Your calls and written messages repeatedly go unanswered. - ✓
The carrier repeatedly requests documents you already delivered. - ✓
The assigned adjuster changes without a clear transition or status update. - ✓
The insurer does not explain what information is still required. - ✓
The estimate omits visible damage or necessary repair work. - ✓
The insurer issues a small payment without clearly resolving the remaining claimed damage.
What to Do When Your Insurance Claim Is Taking Too Long
- Request a written status update.
Ask the insurer to identify what has been completed, what remains outstanding, and whether it needs anything else from you. - Confirm every submission in writing.
Keep delivery confirmations, portal receipts, email timestamps, and copies of every document. - Review the carrier’s estimate carefully.
A delay can conceal a deeper scope or valuation problem. Compare the insurer’s estimate with the actual damage and realistic repair requirements. - Do not rely only on telephone conversations.
Follow important calls with a written summary. - Avoid signing documents you do not understand.
Releases, settlement agreements, sworn statements, and repair authorizations can affect the claim. - Consider professional claim representation.
A licensed public adjuster can evaluate the loss, organize the documentation, prepare the claim presentation, and communicate with the insurer on the policyholder’s behalf.
How Santex Helps With Delayed Property Claims
Santex Public Adjusters helps residential and commercial property owners across Greater Houston understand what has happened in the claim, what documentation may be missing, and whether the insurer’s evaluation reflects the complete loss.
- Review the policyholder’s claim timeline and correspondence
- Document visible and related property damage
- Prepare a detailed repair scope and claim presentation
- Identify missing, omitted, or undervalued damage items
- Respond to reasonable carrier information requests
- Communicate with the insurer about the property claim
When a Delay Leads to Another Claim Problem
The Claim Is Denied
A denial should identify the insurer’s coverage position and the policy provisions it relies on.
The Payment Is Too Low
A payment can be timely and still fail to reflect the full scope or realistic cost of covered repairs.
Repairs Cost More
Contractor findings, hidden damage, code requirements, and material pricing may expose deficiencies in the original estimate.
Delayed Insurance Claim Help Across Greater Houston
Santex Public Adjusters is based in Deer Park and assists property owners throughout Houston and surrounding communities. Local service-area resources include:
Frequently Asked Questions
Texas Insurance Claim Payment and Delay FAQs
How long does an insurance company have to acknowledge a claim in Texas?
In many claims, the insurer generally must acknowledge receipt, begin its investigation, and request the information it reasonably believes will be needed within 15 days after receiving notice. Eligible surplus-lines insurers may have a longer period.
How long can an insurance company investigate a property claim in Texas?
After receiving the materials it requires for final proof of loss, the insurer generally has 15 business days to accept or reject the claim. When it cannot make a decision in that period, it may provide notice that it needs additional time and generally extend the decision period to the 45th day after that notice.
How long does an insurer have to pay after accepting a claim?
The insurer generally must issue payment within five business days after notifying the policyholder that it will pay the claim. Different rules may apply to surplus-lines insurers or when payment depends on an act the policyholder must complete.
Does the 60-day rule mean every Texas claim must be completed within 60 days?
No. The general delayed-payment provision concerns payment delayed more than 60 days after the insurer receives the items, statements, and forms it reasonably requested, when another applicable statute does not establish a different period. It is not a universal promise that every claim will be fully resolved within 60 days of the loss.
Can an insurer ask for additional information after the initial document request?
Yes. An insurer may request additional information during its investigation when the request is reasonably related to evaluating the claim. Keep a written record of every request and your response.
What should I do when my insurance adjuster stops responding?
Send a written request for a status update, document your prior contact attempts, confirm whether any information remains outstanding, and ask for the supervisor’s contact information. Consider a professional claim review when communication remains stalled.
Can a public adjuster force an insurance company to meet a deadline?
A public adjuster is not a court and cannot force an insurer to act. A public adjuster can organize the claim, document submissions, communicate with the carrier, identify unresolved issues, and help move the property claim toward a properly supported decision.
When should I speak with an attorney?
Consider speaking with a qualified Texas attorney when you need legal advice, believe the insurer violated the law, are considering litigation, received a formal legal notice, or face a deadline that could affect your legal rights. Santex Public Adjusters does not provide legal advice.
Get Clarity on Your Delayed Property Claim
You should not have to guess what is happening with your claim. Let Santex review the timeline, documentation, damage scope, insurer estimate, and payment history.
Santex Public Adjusters represents residential and commercial policyholders throughout Greater Houston.
General information only: This page provides general educational information about insurance claim processing. It is not legal advice and does not determine the deadline applicable to a specific policy or claim. Policy terms, insurer type, claim facts, statutory exceptions, and later legal changes may affect the applicable timeline.
Official reference:
Texas Insurance Code Chapter 542

